



Table of Contents
- What Responsible Buy Now Pay Later Usage Actually Looks Like
- The Psychological Triggers That Make BNPL Spend Too Easy
- How to Track BNPL Payments Across Every Provider
- Avoiding Late Fees on Installment Loans: A Practical Playbook
- The Impact of BNPL on Credit Score and Credit History
- Returns, Refunds, and the BNPL Balance That Won't Go Away
- Warning Signs of BNPL Dependency and How to Exit Existing Debt
- Frequently Asked Questions
Last Updated: October 20, 2026
What Responsible Buy Now Pay Later Usage Actually Looks Like
Responsible buy now pay later usage means treating every installment plan as a real bill with a real due date, not as free money.
Buy now pay later splits a purchase into fixed installments, usually four payments over six weeks.
The same feature that makes BNPL convenient makes it dangerous: it removes friction from spending. These habits keep that convenience on your side.
The Four-Payment Structure and What It Demands of You
The standard plan splits a purchase into four equal payments every two weeks, with the first usually due at checkout.
That structure demands two things:
- A cash buffer. The full amount must be available across six weeks, not just today.
- Calendar discipline. Four dates, four providers, four chances to miss one.
A common mistake is counting only the first payment as the "real" cost. The other three still come out of your account.
Essential vs. Non-Essential: The One-Question Filter
Ask one question before every BNPL checkout: Would I still buy this if I had to pay the full amount today?
If the answer is no, the plan is not helping you afford it. It is helping you avoid a decision.
- Essential: work basics, a winter coat, school clothes your kid has outgrown.
- Non-essential: a third dress for one party, trend pieces you will wear twice.
The Psychological Triggers That Make BNPL Spend Too Easy
Retailers design BNPL to feel weightless: the checkout shows a small number, not the full one.
Four triggers do most of the work:
- Payment splitting. A large total becomes four small, friendly numbers.
- Interest-free framing. "No interest" reads as "no cost," which is not the same thing.
- Instant approval. No waiting means no cooling-off period.
- Checkout momentum. The plan appears right when you are most committed to buying.
These triggers stack with impulse buying: one plan feels harmless, but five plans across three providers start to feel like a second rent payment.
How to Track BNPL Payments Across Every Provider
Tracking BNPL payments means building one master list of every active plan, its due dates, and its remaining balance, then checking it on a fixed schedule.
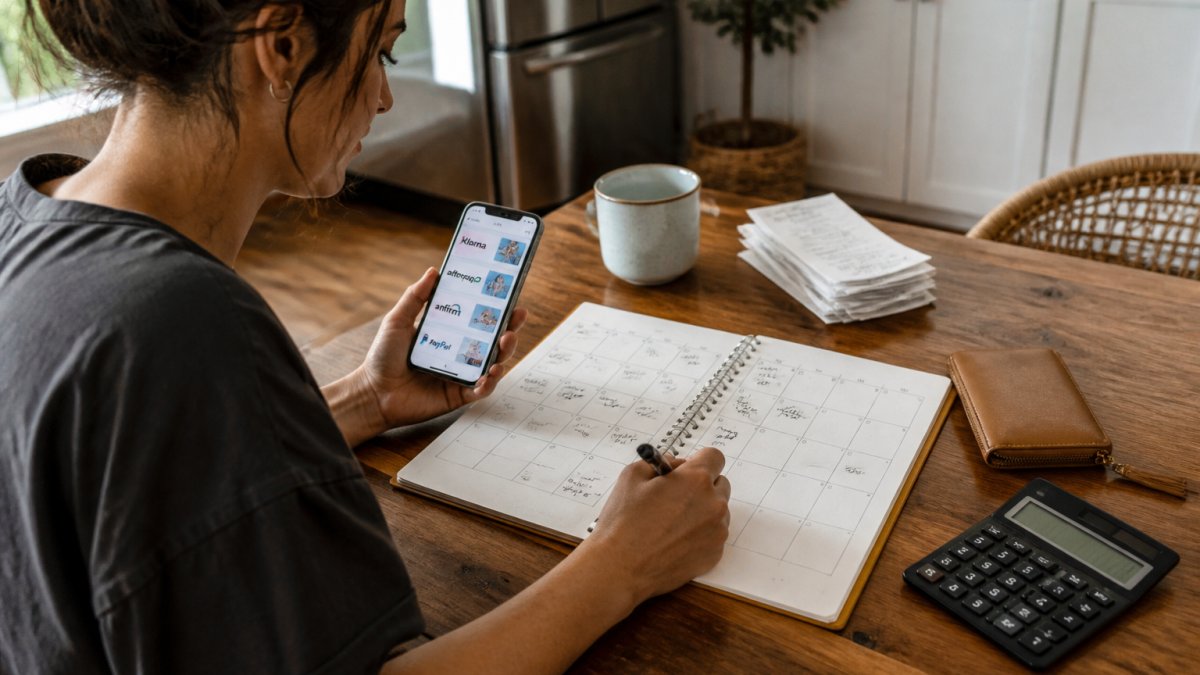
Build a Single Payment Calendar
Put every plan in one place, paper calendar, spreadsheet, or phone calendar app. Include:
- Provider name
- Purchase amount and remaining balance
- Each due date for the next six weeks
Check it once a week, that weekly check turns a list into a habit.
A Concrete Weekly Workflow
A ten-minute weekly review beats a perfect system you never open. Run it the same day each week, Sunday evening or Monday morning works for most people.
- Open every provider app and screenshot the current balance and next due date.
- Update the master calendar with any new plans and any payments already drafted.
- Check the linked account for each upcoming draft and confirm the balance covers it.
- Flag any return in progress and confirm the refund has posted to the plan, not just the store.
- Note the total due in the next 14 days so there are no surprises.
Use Automatic Payments, Then Verify Them
Automatic payments are the best defense against late fees, set them up on every plan, then verify them. Check that the linked card has enough funds before each draft date; a failed autopay still counts as a missed payment with most providers and can trigger fees and account blocks.
Tools That Do the Tracking for You
You do not need a dedicated app to track BNPL, but the right tool removes the memory burden. Three options:
- Your phone's calendar app. One recurring event per plan with the due date and amount in the title, plus alerts three days before and the morning of. Free and works across every provider.
- A spreadsheet. One row per plan, columns for provider, balance, due date, and linked account, sorted by due date. Best if you have more than four active plans.
- A budgeting app that imports transactions. Apps connected to your bank and card accounts show recurring drafts in one feed, catching plans you forgot to log. Check that it supports your providers' accounts first.
Start with the calendar method and move to a spreadsheet once you have more than three active plans. The tool matters less than the weekly check.
Consolidate Due Dates Where Providers Allow It
Some providers let you change a due date or align multiple plans to the same day, turning four scattered drafts into one cluster that is easier to fund and remember. Ask each provider whether a due-date change is available before you open a new plan.
Avoiding Late Fees on Installment Loans: A Practical Playbook
Avoiding late fees on installment loans comes down to three moves: automate, buffer, and consolidate your due dates.
- Automate every payment the day you open the plan.
- Buffer your account with enough to cover the next two drafts.
- Consolidate due dates where providers allow it, so payments cluster instead of scattering.
Late fees are usually small per incident; the real damage is the pattern, since repeated late payments hurt your credit history if the provider reports to the bureaus.
The Impact of BNPL on Credit Score and Credit History
The impact of BNPL on credit score depends on three things: whether the provider reports to the credit bureaus, what type of product you are using, and how much of your available credit the plan consumes. Most guides stop at the first point. The second and third are where scores actually move.
Which BNPL Products Report, and Which Stay Invisible
Pay-in-four plans are typically the least visible.
Longer-term installment products are different. Point-of-sale installment loans, buy-now-pay-later apps with six- or twelve-month terms, and some store-issued financing often do report payment activity to the major bureaus.
Before you assume a plan is invisible, check the provider's terms. The Consumer Financial Protection Bureau's guidance on BNPL explains how these products fit into consumer credit reporting and what disclosures providers must give you.
How Reporting BNPL Accounts Affect Your Score
When a BNPL account reports, it usually behaves like any other installment or revolving account in your credit file. Two mechanisms matter most:
- Payment history. On-time payments can help. Missed payments can hurt, and a single 30-day delinquency can stay on your report for years.
- Credit use. Some reporting BNPL accounts count toward the share of your available credit you are using. High use can lower your score even when you pay on time, because scoring models read high use as overextension.
A practical rule: if a reporting BNPL plan pushes your total credit use above roughly 30% of your available limit, treat that as a warning sign. Paying the plan down early lowers the reported balance and can improve the use ratio.
The Debt Trap Mechanism
The debt trap is not a moral failing but a cash-flow math problem: overlapping plans eat your monthly cash, so you open a new plan to cover the gap, and each new plan adds another due date and another draw on the same paycheck.
Fiscal responsibility starts with knowing your total monthly obligation across every provider. Add up every active plan's remaining payments due in the next 30 days.
Protecting Your Score While Using BNPL
- Ask before you buy. Check the provider's credit-reporting terms at checkout, not after a missed payment.
- Keep reporting plans few. One or two reporting plans are easier to manage than five.
- Pay early when you can. Lower reported balances reduce credit use.
The FTC's consumer advice on buy now pay later covers your rights when plans go wrong, including billing disputes and reporting errors.
Returns, Refunds, and the BNPL Balance That Won't Go Away
Returns do not automatically cancel your installment plan, a complication almost no one warns you about. When you return an item, the refund goes back through the provider, not straight to your card, and until it processes your payment schedule keeps running. You may owe a payment on an item you already sent back.
- Keep the return receipt and tracking number.
- Confirm the refund posted to the plan, not just the store.
- Contact the provider if a payment is due before the refund lands.
Warning Signs of BNPL Dependency and How to Exit Existing Debt
Dependency has clear signals:
- You use BNPL for groceries, gas, or bills.
- You have more than four active plans at once.
- You open a new plan to cover an old payment.
If two or more apply, it is time for an exit plan.
- List every plan with balance and due date.
- Stop opening new plans for 30 days.
- Pay smallest balances first to free up cash flow.
- Use savings or a low-rate debt consolidation option for the rest.
- Delete stored payment info from shopping apps to add friction.
Financial wellness is a habit, not a one-time fix. The FTC's consumer advice on buy now pay later covers your rights when plans go wrong.
| Warning Sign | What It Signals | Fix |
|---|---|---|
| BNPL for essentials | Cash flow shortfall | Build a small buffer fund |
| 5+ active plans | Overextension | Pause new plans for 30 days |
| New plan pays old one | Debt cycle | Consolidate and stop adding |
| Repeated late fees | Calendar failure | Automate and set alerts |
| Avoiding balance checks | Debt anxiety | Weekly 10-minute review |
At Hot Possessions & Glitter Girls, we would rather you use Afterpay, Klarna, or similar options on one planned order than juggle six impulse buys.
We built Hot Possessions & Glitter Girls to make planned shopping easier: over 4,000 apparel items across women's, juniors, and girls' sizes, flexible payment options at checkout, and fast 1-2 day shipping.
Frequently Asked Questions
How do buy now, pay later plans affect your credit score?
Most buy now pay later plans do not report on-time payments to the three major credit bureaus, so responsible usage may not build credit history. The impact of BNPL on credit score comes mainly from missed payments: some providers report delinquencies, and unpaid balances sent to collections can land on your report. A few providers now offer optional reporting that counts on-time payments. Before you sign up, check the provider's credit reporting policy so you know whether the plan helps or only risks your score.
Are there late fees associated with buy now, pay later loans?
Yes, many providers charge late fees on missed installments, and avoiding late fees on installment loans starts with knowing each provider's schedule. Typical structures charge a flat fee per missed payment and cap the total per order. Fees are usually smaller than credit card penalties, but they add up fast when several plans slip at once. Set automatic payments for each plan, keep a buffer in the linked account, and contact the provider before a due date if money is tight, since some will move a payment once without a charge.
Is it better to use a credit card or buy now, pay later?
It depends on what you need from the purchase. Buy now pay later is interest-free when you pay on schedule, which makes it cheaper than a credit card carrying a balance. Credit cards offer stronger consumer protection, rewards, and credit building through reported history. The riskiest choice is stacking both: paying a card balance with a BNPL plan or running several installment loans alongside revolving debt. Pick one method per purchase and pay it off before adding another financial obligation.
What happens if I miss a payment on a buy now, pay later plan?
A missed payment usually triggers a late fee, a freeze on new orders with that provider, and repeated retry attempts on your linked card or bank account. Persistent delinquency can be reported to credit bureaus or sent to collections, which affects your credit history. The quickest fix is to pay the missed installment plus any fee as soon as possible, then check that automatic payments are funded. If you are juggling several plans, pause new purchases until every repayment schedule is current.